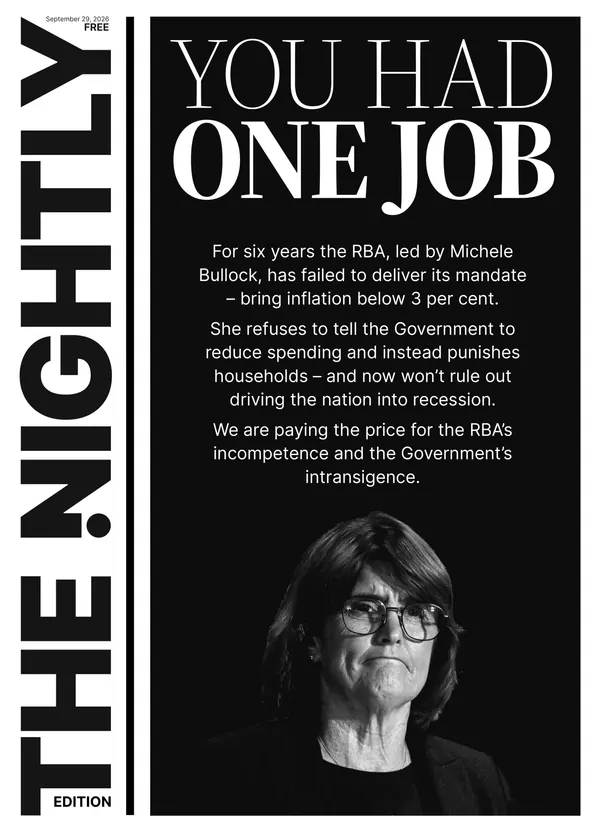
EDITORIAL: Broken model delivers economic pain for borrowers
Like a headmaster caning a schoolboy for something he did not do, the Reserve Bank of Australia has hammered home loan borrowers again by taking the cash rate to a 15-year high of 4.6 per cent.
So around we go again.
Trapped in a vicious economic cycle.
Like a headmaster caning a schoolboy for something he did not do, the Reserve Bank of Australia has hammered home loan borrowers again by taking the cash rate to a 15-year high of 4.6 per cent.
Sign up to The Nightly's newsletters.
Get the first look at the digital newspaper, curated daily stories and breaking headlines delivered to your inbox.
By continuing you agree to our Terms and Privacy Policy.It was the fourth rate rise this year as part of the RBA’s spectacularly unsuccessful attempt to rein in inflation.
Another hike is regarded as likely, which would take the cash rate to an 18-year high of 4.85 per cent and see variable mortgage rates climb above 7 per cent for the first time since the global financial crisis in late 2008.
What does it all mean? Firstly, the RBA is smashing people for a problem generated by factors mainly outside their control.
Secondly, the pain delivered by the RBA is not dealt out equally.
The problem is said to be inflation stuck above the RBA’s target band of 2-3 per cent.
On Tuesday RBA governor Michele Bullock pointed the finger firmly at “domestic capacity pressures”, as well as the Middle East conflict’s impact on oil prices and AI-related demand.
In a take down of Government policies, she said productivity “is doing nothing”.
But Treasurer Jim Chalmers argues the main problem is the Iran war pushing up oil prices, as he tries to deflect any suggestion excessive Government spending in a capacity-constrained economy dragged down by poor productivity is the cause.
Not me, says Dr Chalmers. It is down to Donald Trump. Quite clearly, the Treasurer has washed his hands of it.
Then we come to the RBA. It has just one lever to pull. Cash rates.
And so the RBA sees the answer as penalising a select group — about a third of households, that is, those with mortgages, and small businesses on variable overdrafts.
Inflation, which hits us via soaring fuel prices, supermarket prices, rising insurance and the like hurts everyone.
How is it fair to penalise just that one third of us?
Meanwhile the Government goes on its merry way, throwing cash at favoured interest groups and pretty much anyone whose reaction to a problem is to proclaim they need — no, they have a right to — a hand out.
We are watching the two central players push in opposite directions.
On one hand the RBA pulls its rates lever to drive down inflation. On the other hand the Government pushes the other way by pumping more money into the economy, including “cost of living” handouts.
Mr Trump can’t be controlled. But surely even Dr Chalmers knows he can do something. Like actually facilitating better productivity.
And by cutting Government spending.
So where are we? Costs are smashing us all. And home loan borrowers are being hit with a double whammy, courtesy of the interest rate hammer — even as the plunging housing market is draining away the value of their homes, their biggest asset.
The Albanese Government seems locked into an outdated ideological straitjacket, unable or stubbornly unwilling to help.
What a mess. Our political and economic model is just not working for us.